No First-Loss in Blended Finance
Climate finance has become too comfortable asking who will lose first. Before a project has secured a buyer, demonstrated its technology or established reliable cash flows, the conversation can turn to which government or foundation will protect the investors. We should be asking a more demanding question: what is preventing this investment from working, and who is best placed to address it?
That is the argument behind “No First-Loss in Blended Finance”. I am arguing for an end to first-loss as the default starting point. Public and philanthropic capital should help build investable markets, with loss protection justified by a specific problem and a measurable public benefit.
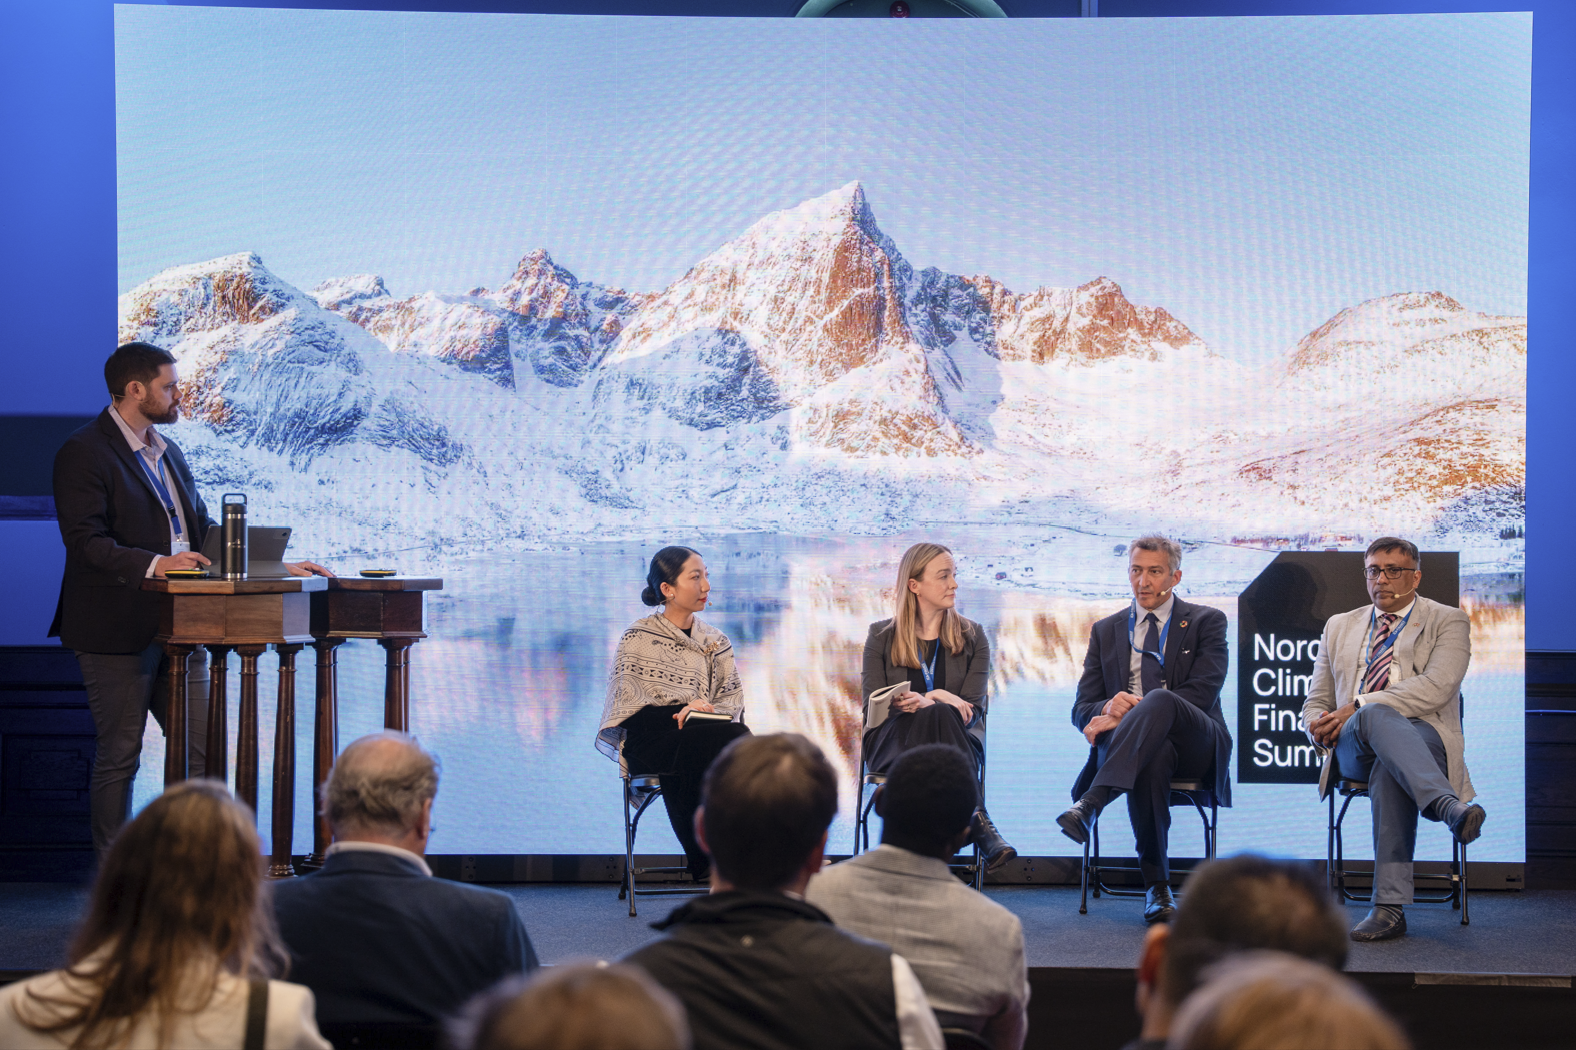
The blended finance discussion at the Nordic Climate Finance Summit exposed why this matters. Moderated by Tim Woodcock, it brought together philanthropy, institutional investment, forestry and project development. The speakers disagreed about instruments, but their experiences pointed to a common weakness: financial structures too often receive more attention than the conditions that make an underlying investment viable.
The stakes are practical. Convergence’s Spring 2025 report recorded approximately $18 billion across 123 blended finance deals in 2024. Private commercial investors contributed $6.9 billion. Yet Convergence also identified weak standardisation and the tendency of some concessional capital to mobilise public commercial finance rather than private investment. A successful transaction is not necessarily evidence of a scalable market. [1]
Tina Min, of SDG Impact Partners and ImpactPhilan, challenged where the conversation begins. Philanthropic capital, she argued, can be most useful long before a fund’s capital structure exists. Feasibility studies, project preparation and market development require funding. Without them, there may be nothing credible for an investment committee to assess.
Her example of electrifying postal delivery in Türkiye illustrated the sequence: preparation first, support for affordability as a portfolio develops, and potentially a first-loss guarantee later. The lesson is that different stages require different interventions. A foundation funding project preparation may unlock more investment than the same foundation waiting to protect a finished fund.
Sanmit Ahuja pushed the criticism further. His examples combined technology performance protection, equipment leasing, supplier participation and committed buyers. The useful principle is to identify individual risks and allocate them to parties able to manage them. A technology supplier, insurer, purchaser and long-term investor have different capabilities; a single concessional cushion cannot substitute for all of them.
But the language needs precision. First-loss describes the order in which losses are absorbed; it does not mean money is destined to disappear. Nor does every first-loss guarantee carry the upside of equity. IFC’s own framework includes debt, equity, risk-sharing and guarantees. The choice of instrument matters more than a more reassuring name. [2]
Caitlin Clarke of BTG Pactual Timberland Investment Group supplied the strongest counterargument to abolishing first-loss altogether. In her account, it helped establish confidence in a reforestation strategy operating at an unfamiliar scale and in markets unfamiliar to some investors. BTG separately documented the strategy’s fundraising close at $1.24 billion in April 2026. Its model combines commercial forestry with ecosystem conservation and restoration. [3]
We should take that evidence seriously. First-loss support can be useful. Clarke’s wider point, however, was that it was one component of an investment proposition built for institutional capital. It could help investors cross a threshold; it could not replace a credible manager, sound governance or a viable business.
Mitch Reznick of Federated Hermes explained another barrier: institutional fit. Investors need to understand where a product belongs in their portfolio and how cash reaches them. A structure may offer protection yet remain too complex to assess, too illiquid to hold or incompatible with an investment mandate. Adding another layer of protection can leave the actual obstacle untouched.
A better approach begins with a risk diagnosis before anyone negotiates a subsidy. Project sponsors should identify whether the binding constraint is preparation, technology performance, construction, demand, currency exposure or liquidity. They should then explain what the proposed intervention changes, what it costs and which risks remain. Commercial insurance or leasing alone does not automatically constitute blended finance; the development contribution and its additional effect should be explicit.
Donors should fund preparation as a serious investment function. Milestone-based grants and, where suitable, recoverable funding can pay for feasibility work, local expertise and transaction design. Foundations also need access to financial structuring expertise so they can negotiate their contribution on informed terms. Philanthropy should have a voice in the design, rather than receive a request to fill the riskiest gap.
Currency risk deserves its own solution. The Currency Exchange Fund, TCX, provides swaps and forward contracts that allow lenders to offer local-currency financing while transferring currency exposure to TCX. This demonstrates a targeted approach to a specific constraint. It does not make the risk disappear; someone with the capacity to manage it assumes it. [4]
We should also invest in the infrastructure of repeatable transactions. Woodcock’s discussion of standard solar contracts points towards shared documentation, comparable operating data and consistent reporting. The Solar Access to Public Capital working group developed standard leases and a commercial power purchase agreement for precisely this broader capital-market context. [5] Aggregating projects becomes more credible when investors can understand and compare their underlying cash flows. A listing alone should never be mistaken for dependable liquidity.
Revenue quality must remain central. During the panel’s discussion of carbon markets, Clarke emphasised the importance of commercial forestry revenues alongside carbon income. Reznick reinforced the need for visibility into revenue. My conclusion is that nature investments should be tested against weaker carbon prices, delayed issuance and changing market rules. Diversification can improve resilience, but it cannot replace environmental integrity. Financial additionality and carbon-credit additionality are separate tests.
Finally, first-loss support should face a transparent public-interest test. Why is it needed? What investment would fail to happen without it? Could a smaller or more targeted intervention achieve the same outcome? How will the support decline as the market develops? The OECD’s 2025 guidance calls for documented additionality, minimum necessary concessionality and a route towards commercial sustainability. [6]
That test must also protect development objectives. The highest mobilisation ratio is not always the greatest public benefit. Some essential services and ecosystems will continue to need grants or public funding. We should not distort their purpose to manufacture an investment product, or exclude difficult markets simply because easier transactions attract more capital.
The ambition is a market that learns. Each supported transaction should leave better information, stronger local capabilities or a financing model that others can use with less subsidy. Success should be measured in durable development outcomes and the investments that become possible next.
Before asking someone to lose first, we should demonstrate what their capital will make possible. That is how blended finance earns its name as a catalyst.
Sources
Panel perspective on Blended Finance drawn from the Nordic Climate Finance Summit 2026. The article cites speakers; the recommendations and thesis are the author’s synthesis.
[1] Convergence, State of Blended Finance 2025 Spring Edition, accompanying release, 21 May 2025.
https://www.convergence.finance/news/urVUbSe6NepM9Gzo9KDdt/view
[2] IFC, How Blended Finance Works; and The Role of Blended Finance in an Evolving Global Context (2025).
https://www.ifc.org/en/what-we-do/sector-expertise/blended-finance/how-blended-finance-works
[2a] IFC report, first-loss guarantee definition.
https://www.ifc.org/content/dam/ifc/doc/2025/role-of-blended-finance-in-an-evolving-global-context.pdf
[3] BTG Pactual TIG, Latin American Reforestation Strategy fundraising announcement, 28 April 2026.
https://timberlandinvestmentgroup.com/btg-pactual-timberland-investment-group-raises-us1-24-billion-for-largest-reforestation-fund-to-date/
[4] TCX, About the fund.
https://www.tcxfund.com/about-the-fund/
[5] National Laboratory of the Rockies, Terms of Service for Example Standard Contracts, Solar Access to Public Capital Working Group.
https://www.nlr.gov/analysis/standard-contracts-tos
[6] OECD, OECD DAC Blended Finance Guidance 2025, Overview, Principle 2.
https://www.oecd.org/en/publications/o